Why your minimum payment is reducing less of your debt these days
Learn why making only the minimum payment shrinks your credit card debt slowly, how interest influences your outstanding balance, and effective strategies to clear it sooner.
Warning: Your minimum payment could be keeping you stuck in debt
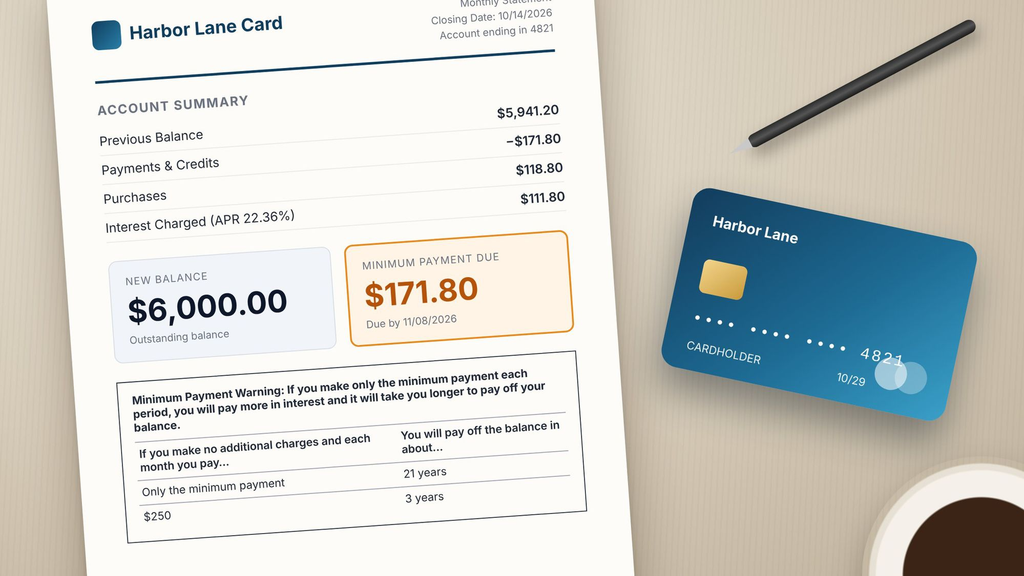
You make your credit card payment each month. So why does your balance hardly ever drop?
The reason could be your minimum payment. With high interest rates, a large portion of your payment goes toward interest instead of lowering what you owe.
Adding new charges and fees can make this issue even more severe.
As of August 2026, the Federal Reserve reported the average annual interest rate on U.S. credit card accounts with interest was 22.36%.
At the same time, Americans owed roughly $1.263 trillion in credit card debt during the second quarter of 2026.
Knowing how your minimum payment is calculated can help you lower interest charges and steadily move closer to paying off your debt.
Why Your Minimum Payment Reduces Less of Your Debt
Your minimum payment is the least amount your credit card company requires by the due date to keep your account in good standing.
However, there’s a downside: paying only the minimum often doesn’t significantly reduce your overall debt.
The Consumer Financial Protection Bureau (CFPB) cautions that making only the minimum payment usually results in paying more interest and extends the time it takes to clear your debt.
There are three main reasons why your debt might become tougher to pay off.
1. High Interest Rates Reduce the Impact of Your Payment
Carrying a balance on your credit card means interest charges are added to your total debt.
The greater your APR (annual percentage rate), the more interest you’ll likely have to pay.
Here’s an example to consider:
- Credit card balance: $5,000
- APR: 22.36%
- Estimated monthly interest: $93.17
- Hypothetical minimum payment: $100
- Amount reducing principal: only $6.83
Keep in mind this example is a basic model and not an exact minimum payment calculation. Actual interest varies with your daily balance, billing cycle, and card terms.
But the key insight remains: high interest rates can leave very little of your payment to actually shrink your debt.
2. Your Minimum Payment Amount May Vary
Credit card companies apply various methods to figure out your minimum payment.
Your minimum payment might be calculated based on a balance percentage, a fixed sum, accrued interest and fees, or a mix of these, depending on your card’s terms.
When your balance decreases, your required minimum payment often lowers too.
While this reduction can ease your monthly bills, sticking to the smaller minimum may slow down your debt payoff.
Tip: If possible, try to keep paying more than the minimum each month, even as that minimum goes down.
3. New Purchases Can Erase Your Progress
Paying down your balance doesn’t always mean it will drop quickly.
Consider this scenario:
- Make a $200 payment on your card.
- Charge $150 in new purchases.
- Accumulate $40 in interest and fees.
As a result, your balance only drops by $10, assuming no other charges or credits.
That’s why it’s important to monitor more than just your monthly payment. Keep an eye on your balance, interest, fees, and any new charges all at once.
What Happens When You Pay Only the Minimum?
Making just the minimum payment can keep your account in good standing. However, consistently doing so can increase the overall cost of your debt.
Here are three key effects to consider.
You End Up Paying More Interest
The longer you carry a balance, the more interest charges will build up over time.
Based on your APR and how you pay, interest may make up a large portion of the total amount you repay.
Your Debt Will Take More Time to Clear
When most of your payment goes toward interest, the amount reducing your principal is very small.
Continuing to add new charges can make it even tougher to pay down your debt.
Less Money Left Over for Your Other Financial Goals
Funds used to cover interest charges aren’t available for other important expenses like:
- Rent and groceries
- Emergency savings
- Retirement contributions
- Other outstanding bills
If your budget is tight, making only the minimum payment might be the most feasible choice for now. What matters most is recognizing the cost involved and striving toward a manageable payoff plan.
Ways to Make Your Minimum Payment Reduce More Debt
You don’t have to completely change your financial habits all at once.
Begin by taking some simple, manageable actions.
Try to Pay More Than the Minimum When You Can
For example, if your minimum payment is $100 but you’re able to pay $150, putting that extra $50 toward your balance will help cut down your debt faster.
Reducing your principal also means you’ll pay less interest later on.
But avoid pushing your budget so much that you have to borrow more just to cover basic needs.
Pick a payment amount that you can consistently afford each month.
Examine Your APR and Credit Card Statement
Your credit card statement each month can reveal why your balance isn’t going down.
Look closely at these points:
- Your current APR
- The interest charged
- Your minimum payment
- Your payment due date
- Your outstanding balance
Now, consider this question:
Is my balance truly going down?
Look at your balance month over month. If there’s little to no change, take a closer look at your interest fees and any recent charges.
Request a Lower APR from Your Card Issuer
If high interest rates are making repayment tough, reach out to your credit card provider.
Inquire whether you might be eligible for:
- Reduced interest rate
- A hardship assistance plan
- Alternative payment options
While approval isn’t assured, reaching out could uncover a more affordable repayment plan.
Another option is to explore balance transfer cards or debt consolidation loans.
Before agreeing to any offer, review transfer fees, when the promotional rate ends, and what the standard APR will be afterward.
A lower advertised interest rate doesn’t always translate to a more affordable option.
Review Your Repayment Estimate
Credit card statements that apply will disclose how long and how much it could cost if you only pay the minimum each month.
Your statement might also include an estimated monthly payment amount that would clear your balance within 36 months.
Take a close look at that estimate and see how it fits with your budget.
If the recommended payment feels too steep, pick a manageable amount and adjust your plan as your financial situation evolves.
Why October Is an Ideal Month to Reassess Your Credit Card Debt
October marks National Financial Planning Month across the United States.
This month serves as a perfect prompt to evaluate your expenses, current debts, and financial objectives before year-end.
On October 15, 2026, the American Bankers Association Foundation held its annual Get Smart About Credit Day, a campaign focused on improving credit knowledge.
With the holidays and travel coming up, a bit of preparation can help you steer clear of unnecessary credit card debt.
Take advantage of October by following these five steps:
- List your balances and APRs. Identify your most expensive debts;
- Review your interest charges. See how much of each payment reduces your principal;
- Set a realistic payment target. Protect your budget for essential expenses;
- Plan holiday spending. Decide what you can afford before shopping;
- Track your progress. Compare your balance every month.
You don’t need to wipe out your debt before year’s end. The aim is to start the new year with a clearer, more manageable plan.
When to Reach Out for Help With Credit Card Debt
If your debt balance keeps climbing or you struggle to meet your minimum payments, it’s important not to overlook the issue.
The Consumer Financial Protection Bureau advises contacting your credit card issuer right away if you’re having difficulty making payments.
Inquire about options like hardship programs, lower interest rates, or modified payment plans.
Another option is to reach out to a trustworthy nonprofit credit counseling service.
Watch out for companies that:
- Promise to erase your debt completely.
- Require large upfront payments.
- Advise you to stop contacting your credit card issuer.
These are often red flags for potentially unsafe debt relief options.
If covering essentials is a challenge, focus on basic needs first and get advice from trusted sources before agreeing to any repayment plan.
Author’s Perspective
Dealing with credit card debt can be disheartening, especially when it feels like you’re doing everything right.
You make your payments each month, yet your balance hardly seems to decrease.
The issue is that your minimum payment is structured to fulfill a payment obligation, not necessarily to help you pay off your debt quickly.
With high interest rates, even a small increase above the minimum payment can make a significant difference.
That said, you shouldn’t cut back on necessary expenses just to accelerate debt repayment.
Begin by checking your APR, getting familiar with your statement, and pinpointing one practical adjustment.
You could pay a bit extra, avoid charging new purchases on a card with a balance, or ask your issuer about lowering your interest rate.
You don’t have to clear your debt instantly. It’s important to grasp why your minimum payment reduces so little of your balance and create a doable plan to improve that.
Recommended Content
2027 social security raise
Learn when payments change, how much you may receive, and how Medicare costs affect your budget.
Continue Reading * You will remain on the current website