The reason your card’s yearly fee just won’t stop rising
Wondering why your credit card’s annual fee keeps climbing? Discover the factors behind these hikes and find out how to determine if your card remains a good deal.
Is your credit card getting pricier? Beware of rising annual fees
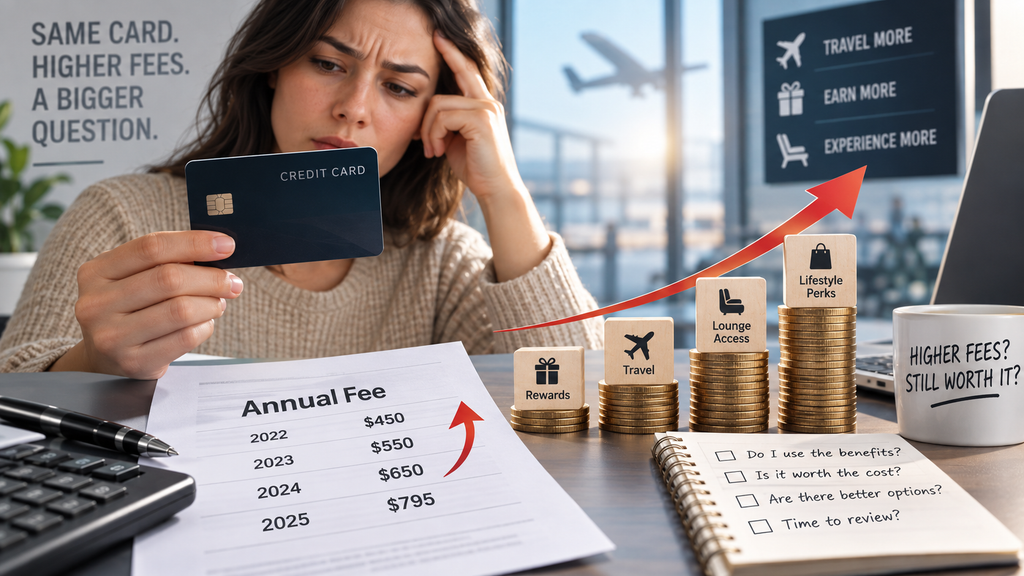
Your credit card’s annual fee may be increasing because issuers are raising charges for premium rewards, including more travel and lifestyle perks, tweaking card economics, and targeting higher-spending customers with repositioned products.
A bigger fee doesn’t necessarily mean the card is a better or worse value.
The main consideration is whether the perks you actually use justify the higher annual cost.
What’s Driving the Increase in My Credit Card’s Annual Fee?
A credit card’s annual fee may rise when the issuer updates the card’s pricing structure or modifies its benefits.
Many premium cards have added more travel credits, lounge access, rewards, and lifestyle perks while simultaneously increasing their annual fees.
For instance, changes to premium cards have led some annual fees to approach or exceed $800 per year.
The key difference lies between the value the issuer promotes and the actual value you gain from it.
What Causes Credit Card Annual Fees to Go Up?
Common reasons include the following:
- Introduction of travel credits
- Expanded access to airport lounges
- Increased rewards rates
- New perks for hotels or dining
- Extra statement credits
- Modifications to rewards programs
- Higher expenses for premium rewards
- Targeting higher-spending customers
Are Annual Fees Increasing Across Credit Card Offers?
Fee hikes have been especially noticeable among premium credit cards.
The Federal Reserve Bank of New York noted that U.S. credit card debt hit $1.26 trillion in Q2 2026, underscoring the ongoing role of credit cards in household budgets.
At the higher end of the market, some credit cards now carry annual fees of several hundred dollars, with a few products nearing or surpassing $800 in yearly charges.
What’s Driving Premium Credit Cards to Increase Their Annual Fees?
Premium cards are competing more by bundling a range of travel and lifestyle perks together.
As a result, a steeper fee often reflects a pricier package of benefits, though having more perks doesn’t always translate into greater value for every user.
Travel Credits Can Help Offset a High Annual Fee
Imagine a card with a $795 annual fee that offers $300 in travel credits.
The straightforward math is: $795 minus $300 equals $495.
However, that $300 only has full value if you would have spent that amount on qualifying purchases regardless.
If you redeem just $150 of the credit, then your real value is closer to $150, not the full $300.
Understanding this difference is key when assessing premium credit cards.
Airport Lounge Access Holds Different Value for Various Travelers
Access to airport lounges can be a great perk for those who travel often.
If you fly multiple times a year, having lounge access might replace expenses you’d usually incur at the airport.
But for those who travel infrequently, this benefit may offer little real advantage.
Don’t judge a perk by its listed price—assess it based on the actual savings it provides you.
Rewards Only Hold Value When They Align with Your Spending Habits
Higher rewards rates can help balance out an annual fee if they apply to purchases you’re already making.
However, increasing your spending just to earn rewards often defeats the whole purpose.
For instance, if a card gives extra points on dining, that doesn’t justify charging an unnecessary $500 meal as a way to save money.
Your rewards should reflect what you normally spend, not push you to spend more.
Should You Keep a Credit Card After Its Annual Fee Goes Up?
Before deciding to keep, modify, or cancel your card, consider several important factors.
Weigh It Against a No-Fee Credit Card
Don’t limit your comparison to just other premium cards.
Look at its overall yearly value compared to a card with no annual fee.
Check With Your Issuer About Switching Products
Before you decide to close your card, see if your issuer offers the option to switch to a different product.
Depending on your issuer and specific account, you might be able to downgrade to a card with a lower or no annual fee.
Options vary depending on the card issuer.
Is It Legal for a Credit Card Company to Raise Your Annual Fee?
In general, federal regulations allow certain increases to annual or monthly maintenance fees after the first year, as long as the issuer complies with the required rules.
Regulation Z along with guidance from the CFPB sets out the notification standards for specific changes to credit card terms.
Certain adjustments require at least 45 days’ advance notice, though the exact timing depends on the nature of the change.
How Much Notice Does a Credit Card Issuer Have to Give?
When changes fall under Regulation Z’s scope, cardholders are typically provided with advance notification.
The notice must outline key details such as:
- The updated fee amount
- The date the change begins
- Which account terms are impacted
- Any rights or choices you have
Be sure to read the issuer’s notice carefully, as rules can vary by fee and account details.
Is It Possible to Avoid Paying an Annual Credit Card Fee?
In some cases. You might consider options like these:
- Switching to a no-fee card from the same issuer;
- Inquiring about possible product changes;
- Evaluating the card against other options;
- Contacting your issuer to ask about retention offers;
- Closing the card after weighing credit impacts.
Does Canceling a Credit Card Affect Your Credit Score?
Closing a credit card may influence elements used in credit scoring.
An important factor to keep in mind is credit utilization.
What’s the Best Approach If You Carry a Credit Card Balance?
If you carry a balance month after month, the annual fee isn’t the only cost you should be focusing on.
According to the Federal Reserve Bank of New York, U.S. credit card balances hit $1.26 trillion in the second quarter of 2026.
If you’re carrying revolving debt, the interest charges typically outweigh any benefit you might get from rewards.
Should You Increase Spending to Make Up for an Annual Fee?
No financial analysis should be based on spending more than you normally would.
When a card costs $500 annually, spending extra thousands just to earn rewards can end up raising your costs instead of lowering them.
The aim shouldn’t be to rack up enough rewards to justify extra spending.
Instead, focus on getting the most value from purchases you were going to make anyway.
Author’s Opinion
A rising credit card annual fee calls for recalculating its value—especially when the increase is several hundred dollars.
It’s not about whether the issuer has added more perks. What matters is if those perks align with how you actually spend, travel, and use your card.
If you already take advantage of the credits and rewards offered, the higher fee might be balanced by benefits you’d have bought regardless.
If you don’t use those benefits, the stated value can give a misleading impression for your own finances.
The easiest way to judge is to ask: what did I actually save over the past year, and how much did the card cost me?
That calculation offers a clearer view than relying on the promotional value placed on every perk.
Also, if you carry a balance, keep in mind that prioritizing rewards only makes sense after you’ve accounted for your interest charges.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website