Loan Rates: Don’t Miss the Crucial September 30 Deadline
Discover how setting up automatic payments by the September 30 deadline can help reduce interest rates on qualifying federal student loans.
Is Your Loan Interest Rate Too High? What to Know Before September 30
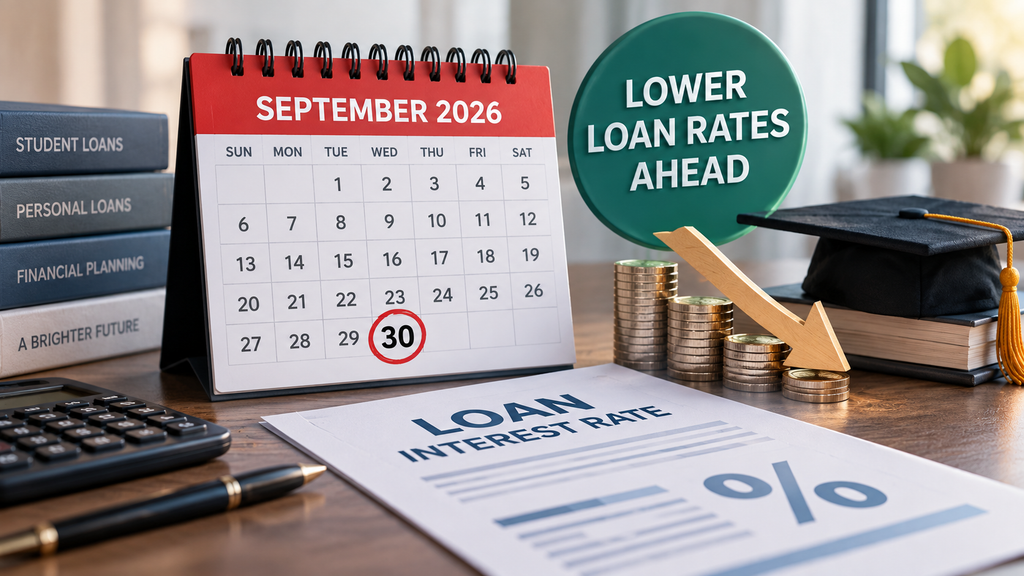
September 30, 2026, marks a crucial cutoff date for federal student loan borrowers who qualify for certain benefits.
By signing up for automatic payments by 11:59 p.m. on that day, you could be eligible for a temporary 1% interest rate discount on your loan, effective through June 30, 2028, the U.S. Department of Education states.
This deadline doesn’t apply to all loans. It specifically affects eligible federal student loans tied to the Auto Pay interest rate reduction.
If you want to reduce your borrowing expenses, here’s what the September 30 deadline involves, who is eligible, how the rate cut works, and what to verify before the deadline arrives.
Understanding the September 30 Loan Interest Rate Deadline
The September 30 cutoff marks the final day for eligible federal student loan borrowers to sign up for Auto Pay and qualify for a temporary 1% reduction in their interest rate.
Starting July 1, 2026, the U.S. Department of Education raised the Auto Pay interest rate discount from 0.25% to a full 1%.
Borrowers who sign up by September 30 will enjoy this temporary 1% rate cut through June 30, 2028.
Why Is the September 30 Deadline Important?
Reducing your loan interest rate can lower the total interest that builds up on your outstanding student loan balance.
The effect varies based on your loan balance, repayment plan, and how much time is left on your loan.
For instance, someone owing $30,000 could save about $300 annually in interest by dropping from a 7% to a 6% rate, before factoring in any principal payments.
This example is for illustration only and doesn’t represent exact savings for any individual borrower.
Does the September 30 Deadline Apply to Every Loan?
No. It’s crucial to recognize this important distinction.
The September 30 deadline doesn’t require refinancing personal loans, mortgages, auto loans, or private student loans by that date.
The temporary 1% rate reduction applies only to qualifying federal student loans with Auto Pay enrollment.
Who Is Eligible for the 1% Interest Rate Reduction on Loans?
Federal student loan borrowers who sign up for Auto Pay by September 30, 2026, may qualify for the temporary 1 percentage-point interest rate reduction.
The Department of Education states that the enhanced interest rate reduction applies to qualifying Direct Loans issued on or after July 1, 2012.
You should verify your specific eligibility by checking with your loan servicer.
What Happens If You’re Already Enrolled in Auto Pay?
If you’re currently signed up for Auto Pay, there’s typically no need to re-enroll.
The updated program raises the overall Auto Pay discount to 1 percentage point, so borrowers who had a 0.25% reduction can now benefit from an extra 0.75 percentage-point cut.
Visit your loan servicer’s portal to verify how the discount is applied to your loans.
The Importance of Loan Interest Rates for Borrowers in 2026
The cost of borrowing continues to be a key financial concern for many American households.
On September 16, 2026, the Federal Reserve increased the federal funds target range by 0.25 percentage points to 3.75%–4%.
In addition, the Federal Reserve Bank of New York revealed that overall U.S. household debt hit $18.8 trillion in the second quarter of 2026.
These numbers don’t set the exact rate an individual borrower will get, as loan pricing varies by type.
Still, they explain why many consumers keep a close eye on borrowing rates.
How Does the Federal Funds Rate Affect My Loan?
The federal funds rate isn’t the same as the interest rate on your personal or student loan.
Rather, it’s the rate banks charge each other for overnight loans of reserve funds.
Monetary policy shifts can impact the overall financial landscape, but how much they affect a specific loan varies depending on the loan type and how its interest rate is set.
This difference is crucial to keep in mind when you see news about loan rates “dropping” or “increasing.”
Loan Interest Rate vs. APR: What’s the Difference?
The interest rate is the percentage charged on the amount you borrow, while the APR offers a more comprehensive view of the yearly loan cost, including some fees.
When comparing personal loans, APR is especially helpful because loans with identical interest rates might carry different fees.
Why This Is Important When Comparing Personal Loan Options
NerdWallet found that APRs for personal loans typically vary between about 6% and 36%, influenced by both the lender and the borrower’s profile.
Their September 2026 report also highlighted notable differences in average prequalified APRs depending on credit history.
This means the rate another borrower gets won’t necessarily match the rate you’ll be offered.
How to Find Your Loan Interest Rate Before the September 30 Deadline
The quickest way to see if this deadline affects you is by reviewing your federal student loan account and checking your Auto Pay enrollment.
Here’s how to do it:
Step 1: Review Your Current Loan Interest Rate
Sign in to your federal student loan servicer’s website.
Note down the interest rate for each of your loans.
Step 2: Verify Your Auto Pay Enrollment
Find the payment settings area in your account and confirm whether Auto Pay is currently enabled.
If Auto Pay isn’t set up yet, follow the enrollment steps given by your loan servicer.
Step 3: Confirm Your Interest Rate Discount
Check for details that indicate if the Auto Pay interest rate discount is applied to your loan.
If you don’t see the details, reach out to your loan servicer for help.
Step 4: Verify Your Bank Account Information
Confirm that the bank account linked to Auto Pay is active and has enough funds to cover your scheduled payments.
Step 5: Keep a Copy of Your Confirmation
Once enrolled, be sure to save your confirmation email or enrollment receipt for your records.
Keeping this confirmation can be helpful if you need to address any issues with your account later on.
Is the September 30 Deadline Relevant for Personal Loans?
No. Borrowers with personal loans won’t automatically get a 1% interest rate cut by the September 30 deadline.
If your personal loan carries a high interest rate, there may be alternative ways to lower your borrowing expenses.
Some options to consider include:
- Comparing different refinancing options
- Consulting your current lender about lower rates
- Boosting your credit score before applying
- Evaluating loans by their APR
- Shortening the loan term when possible
However, when considering refinancing, focus on the overall cost of the loan rather than just its stated interest rate.
What Are the Consequences of Missing the September 30 Deadline?
Failing to meet this deadline doesn’t mean you lose all chances to lower your borrowing costs.
Still, you might miss out on the temporary boosted Auto Pay discount available through the September 30 enrollment period.
Here’s what happens if you miss the deadline:
- Check your federal student loan account.
- Contact your servicer about available benefits.
- Review your repayment options.
- Check other high-interest debts.
- If you have personal loans, compare refinancing options separately.
It’s important to separate this federal student loan benefit from broader chances to refinance or renegotiate other kinds of debt.
Money Checklist for Borrowers: September 2026 Edition
September is a great time to reassess your borrowing expenses.
During September, the Bureau of Labor Statistics will release key economic data, including the August jobs report on September 4, the Consumer Price Index for August on September 11, and the JOLTS report on September 29.
While these reports don’t directly set your specific loan interest rate, they help illustrate the overall economic environment.
Take Stock of Your Debts
Put together a straightforward list that includes:
- Loan balance
- Loan interest rate
- APR
- Monthly payment
- Remaining term
- Possible fees
Spot Where Your Costs Might Be Highest
Begin by focusing on debts that come with the steepest interest rates.
Credit cards and certain personal loans often have much higher rates compared to other types of consumer debt.
Look Into Possible Discounts
Check if your lender or loan servicer offers perks or discounts related to:
- Enrollment in Auto Pay;
- Established customer history;
- Participation in certain repayment plans;
- Additional qualifying criteria.
Always confirm the details directly with your loan provider.
Author’s Opinion
The September 30 deadline is important to grasp because it signifies a distinct, well-defined chance for qualified federal student loan borrowers, not a universal cutoff that impacts all loans nationwide.
Qualified borrowers should check their Auto Pay status before the cutoff to confirm they’re receiving any eligible interest rate discounts.
For everyone else, the key takeaway is clear: avoid making borrowing choices based only on headlines about loan interest rates.
When evaluating borrowing options, consider the loan interest rate, APR, fees, monthly payments, repayment length, and overall costs together.
This approach helps you better understand the true cost of the loan and decide if switching loans fits your financial goals.
Recommended Content
Why your card’s annual fee keeps climbing
Learn what drives increases and how to calculate whether your card is still worth it.
Continue reading * You will remain on the current website