Reasons savings rates could start rising once more
Savings rates could increase once more. Discover how the Fed's latest moves affect your finances and get tips on choosing the best high-yield savings accounts.
Calling all savers: savings rates might be set to rise soon
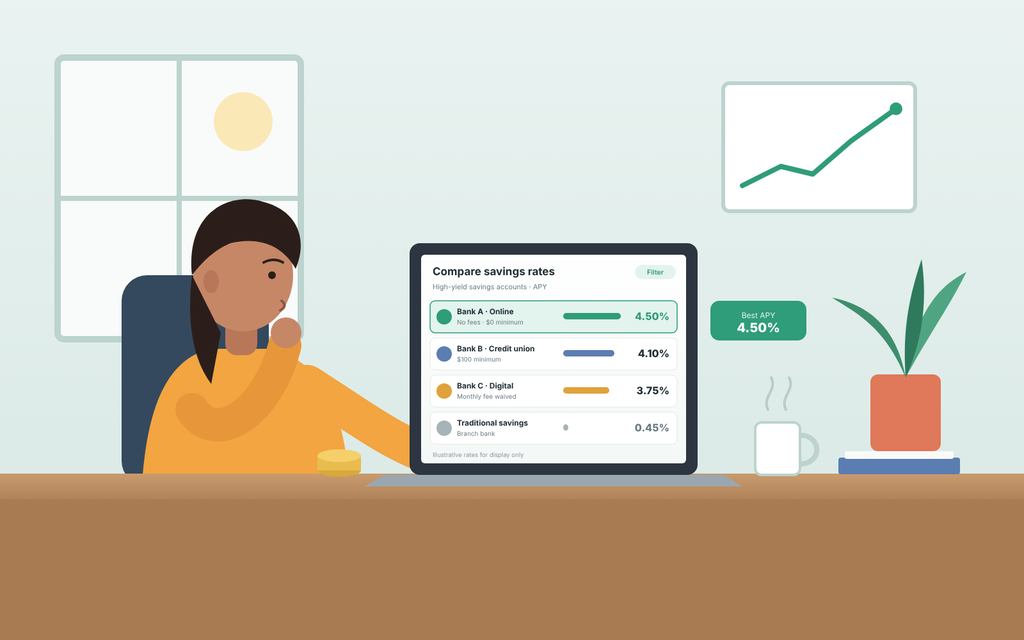
Is your savings account delivering a solid interest return? If you’ve left money parked without checking your APY lately, you might be missing out on higher earnings.
Savings rates could increase again in 2026, opening up fresh chances for Americans to get more from their money.
However, there’s a catch: rising interest rates don’t always mean every bank will boost what they pay you.
Here’s what to understand before you make your next financial decision.
Reasons Savings Rates Could Increase Again
Several key elements affect savings rates, such as:
- Federal Reserve policies;
- Inflation levels;
- Bank competition;
- Demand for deposits.
In September 2026, the Federal Reserve increased its target rate range to 3.75%–4.00%.
This is important because shifts in market interest rates often affect the rates banks offer on savings accounts.
That said, each bank decides its own deposit interest rates independently.
An increase in the Fed’s rates doesn’t necessarily lead to a higher APY on your savings.
How the Federal Reserve’s Upcoming Decision Might Impact You
The Federal Reserve’s meeting on October 27–28, 2026, is a key date that savers should keep an eye on.
According to a Reuters survey published on October 20, most economists expect the Fed to pause rate hikes in October, with a possible increase coming in December.
These predictions are not guaranteed decisions.
If rates increase again, some banks might raise their savings yields, while others could keep their APYs the same.
The main point: Keep an eye on your account instead of expecting your bank to boost your rate automatically.
How Inflation Impacts Your Savings
Higher interest returns don’t tell the entire story.
Inflation is another important factor to keep in mind.
According to an October report by the Associated Press, U.S. consumer inflation was 3.7% year over year in September 2026.
As prices increase, the value of your money declines.
For instance, a savings account yielding 0.50% APY would fall short of matching 3.7% inflation before taxes.
While your account balance might increase, its purchasing power could still decrease compared to the previous year.
Factors That Could Push Savings Rates Higher
There are three main factors to keep an eye on.
1. Ongoing Inflation Pressure
If inflation stays above the Fed’s 2% goal, decision-makers might keep interest rates high or even raise them further.
This situation could motivate some banks to boost their savings rates to attract deposits.
On the other hand, if inflation slows down more quickly than anticipated, the opposite effect could occur.
2. Rivalry Among Banks
Banks vie to attract deposits from customers.
A common strategy to draw in new clients is offering savings accounts with attractive, high interest rates.
This can give you a chance to earn better returns even if your current bank doesn’t raise its rates.
Compare these factors before making a switch:
- Annual percentage yield (APY);
- Fees charged monthly;
- Required minimum balances;
- Options for withdrawals and transfers;
- Any eligibility criteria.
Make sure to verify the current rate directly on the bank’s official site.
3. How Changes in Bank Funding Affect Rates
Banks don’t always adjust savings rates immediately following Federal Reserve changes.
Some banks increase savings rates promptly, while others make smaller changes or leave rates the same.
Variable APYs can also be reduced by banks when market conditions shift.
Don’t rely on your bank to alert you to better rates. Stay proactive and review your options often.
How to Respond If Savings Rates Start Increasing Again
You don’t have to guess the Fed’s next move to make smarter choices with your savings.
Begin by following these five practical steps.
1. Verify Your Current APY
Check your account details via your bank’s online portal or mobile app.
Pay attention to:
- Your current APY;
- Monthly fees;
- Minimum balance rules;
- Terms tied to promotional rates.
If your current rate is much lower than other offers, figure out how much you could gain by switching accounts.
2. Explore High-Yield Savings Options
High-yield savings accounts can provide better interest rates while keeping your funds easy to access.
However, don’t base your choice solely on the advertised APY.
Make sure to review fees, account conditions, and rate terms before opening any new account.
3. Consider Inflation and Tax Impacts
Your APY doesn’t reflect your actual net gain.
For example, if your account yields 4.35% and inflation runs at 3.7%, your estimated real return before taxes is about 0.65 percentage points using the simple difference method.
Your earnings could shrink further once taxes are applied.
Interest earned on bank accounts is typically taxed by the IRS according to relevant regulations.
4. Get Ready for Holiday Spending
October is a great opportunity to revisit your budget before holiday shopping and travel costs pile up.
Think about dividing your savings into distinct goals such as:
- Emergency funds.
- Holiday expenses.
- Monthly bills.
- Long-term savings.
Reserve funds you’ll need soon in an account that offers easy access.
There’s little point in chasing a marginally higher rate if you can’t easily access your funds when necessary.
Is It Possible for Savings Rates to Drop Instead?
That’s right. Even following a stretch of increases, savings rates can still decline.
Should inflation ease and the Federal Reserve decide to lower interest rates, banks might respond by cutting APYs on accounts with variable rates.
Banks may also change their rates independently, influenced by competition and their own funding requirements.
That’s why simply going after the highest advertised APY isn’t always your best bet.
Focus instead on the overall benefits the account offers:
- Attractive returns.
- Minimal or no fees.
- Easy account access.
- Protected deposits.
- Transparent terms.
Base your choices on confirmed rates rather than speculation about future market moves.
Author’s Opinion
The chance that savings rates will increase is promising, but the real advantage lies in ensuring your funds are earning a strong return right now.
A lot of people keep their savings parked in the same account for years without ever checking the interest rate they’re getting.
This habit can lead to missing out on hundreds of dollars in possible interest earnings.
On the other hand, chasing the top advertised rates without checking for fees or account terms might cause avoidable issues.
Here’s my advice: review your current APY, compare offers from different banks, and ensure your money stays easy to access when needed.
You don’t have to guess the Federal Reserve’s next action to make better choices about your savings.
Recommended content
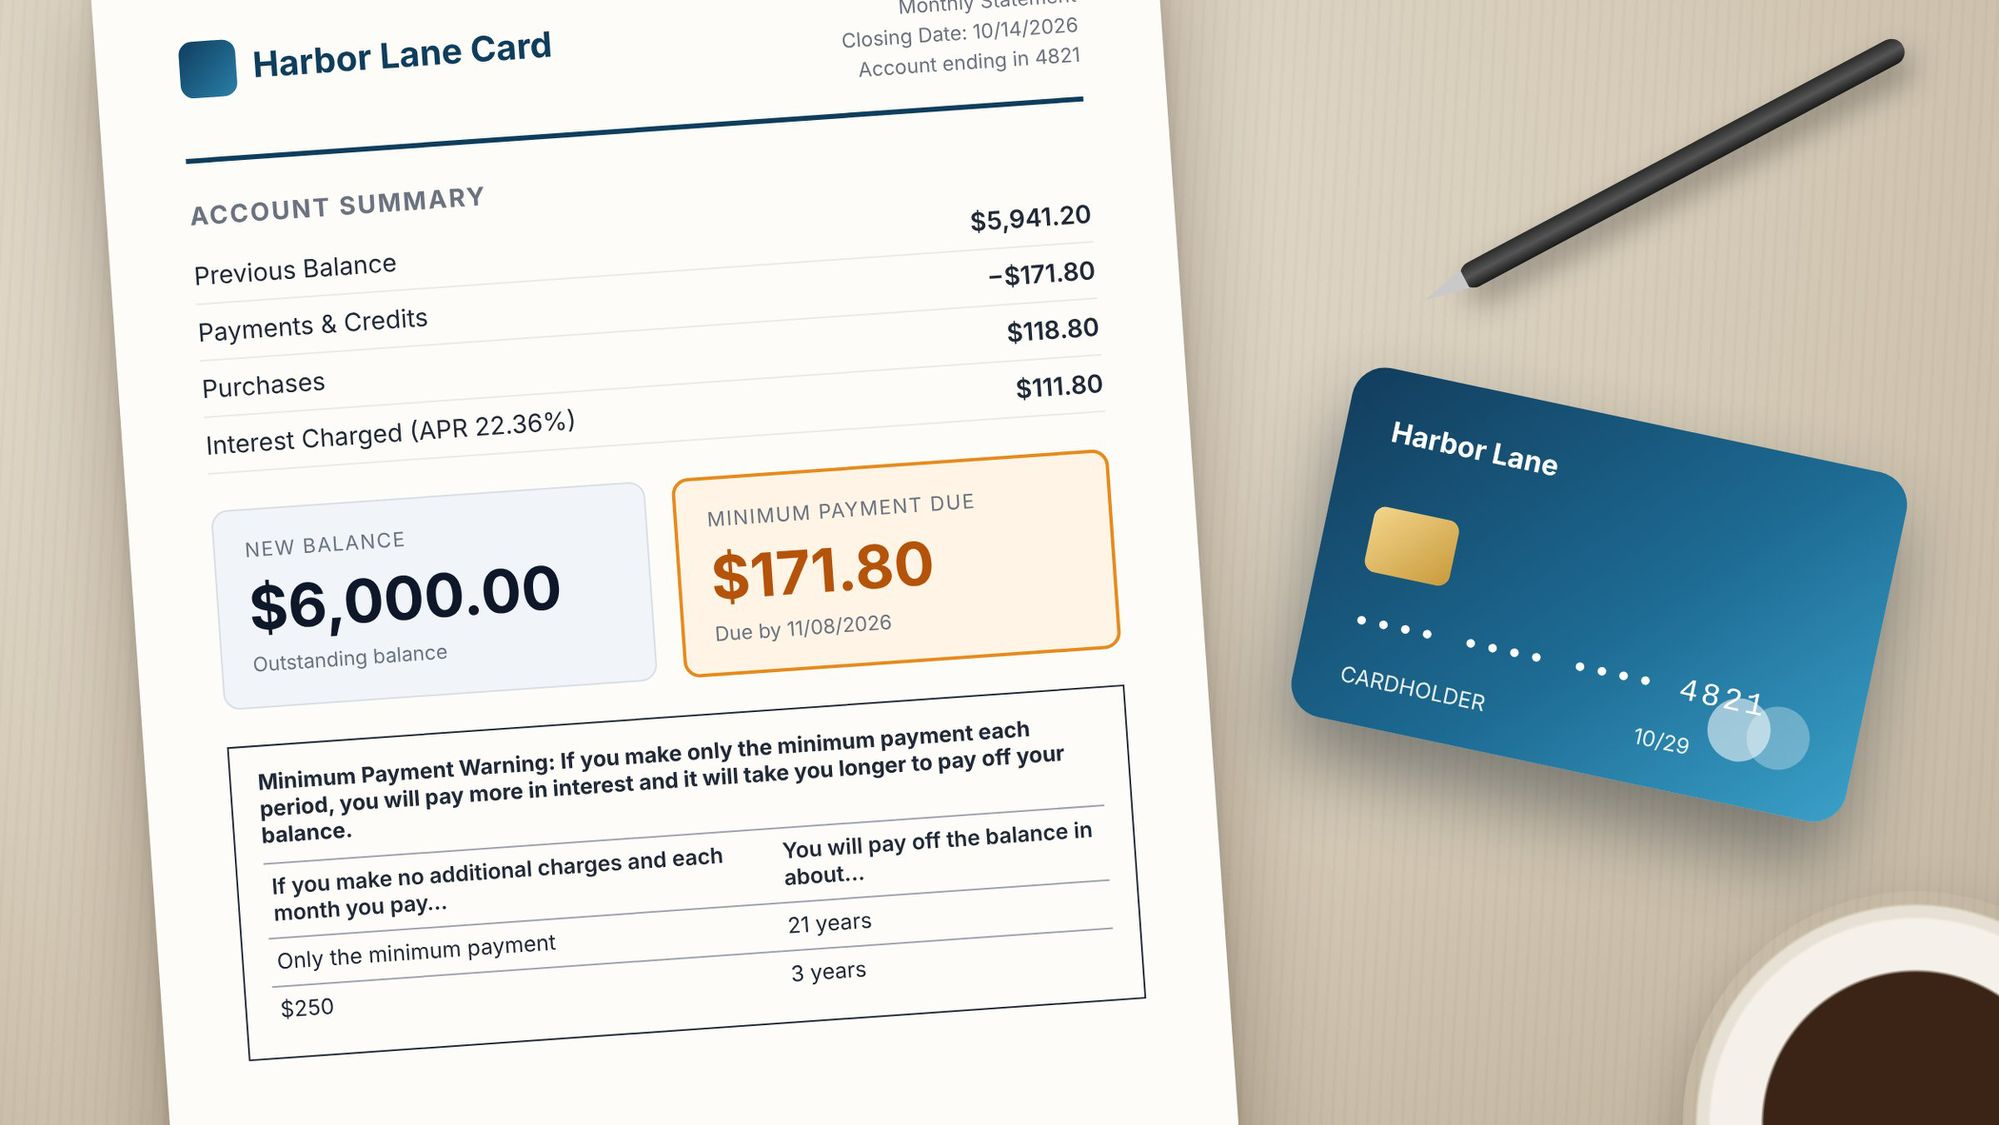
Why your minimum payment
Discover why your minimum payment reduces less credit card debt, how interest affects your balance, and what you can do to pay it off faster.
Continue Reading * You will remain on the current website